Introduction
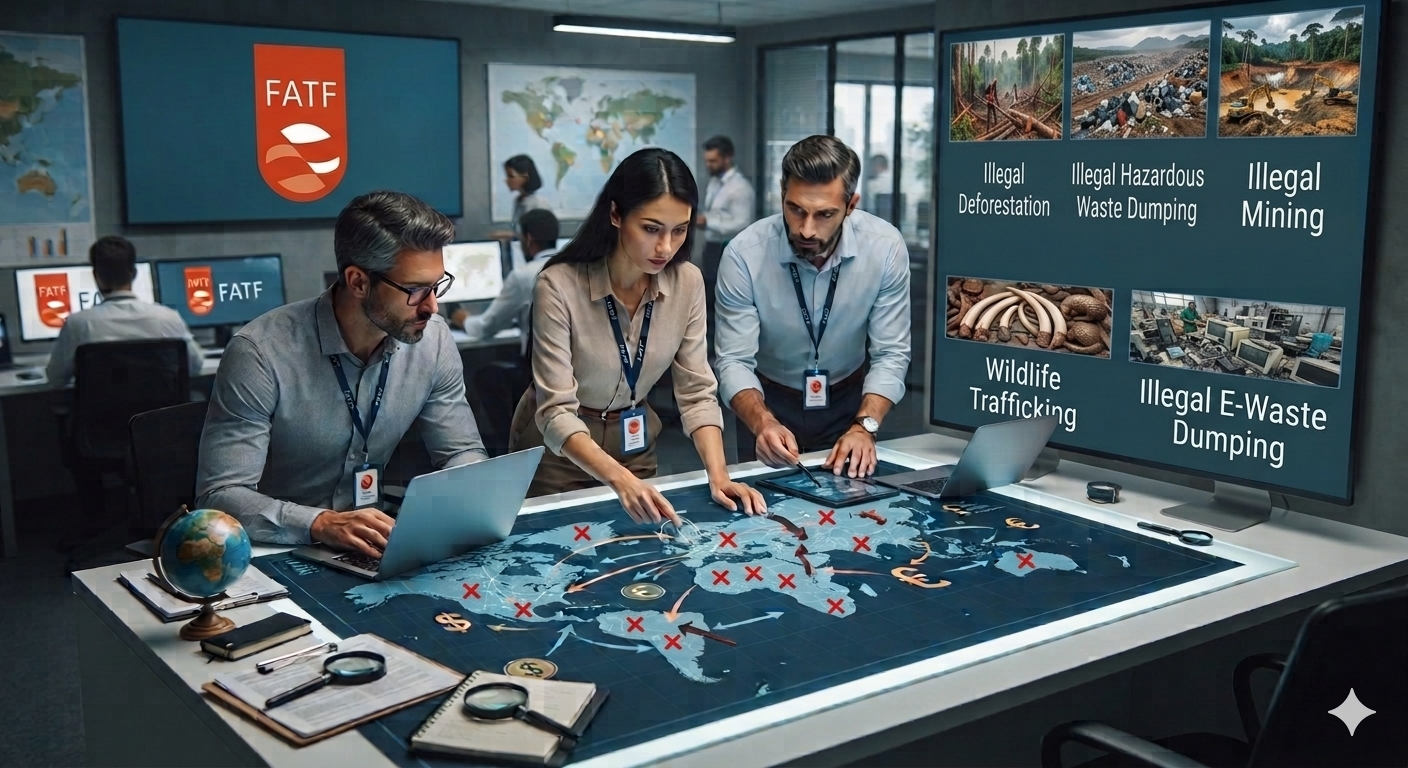
Environmental crime has traditionally been viewed as a conservation, regulatory or criminal-law problem. Illegal wildlife trafficking, illegal logging, illicit mining, illegal fishing, waste trafficking and other forms of natural-resource crime have generally been investigated through the seizure of trafficked natural resources, arrest of offenders and prosecution of the underlying environmental offence.
The Financial Action Task Force (FATF) has helped change this perspective by placing the financial dimension of environmental crime within the global anti-money laundering (AML) framework. FATF estimates that environmental crimes generate approximately USD 110–281 billion in criminal gains annually. FATF standards require countries to criminalise money laundering for a range of environmental offences, while its Glossary expressly identifies environmental crime as a designated category of offences.
The central premise is straightforward: environmental crime generates substantial illicit profits, and following those profits can expose the organisers, financiers, facilitators and beneficiaries who may remain beyond the reach of conventional environmental investigations.
Financial Investigation of Environmental Crime
The conceptual shift is important. Instead of asking only:
Who poached the animal, illegally mined the mineral or cut the timber?
Financial investigation must asks:
Who financed the activity, who received the proceeds, through which accounts and companies did the money move, who ultimately benefited, and what assets were acquired with it?
This approach can potentially take an investigation from the individual offender to the wider criminal network.
Understanding How Environmental Proceeds Are Laundered
The principal money laundering methods and typologies identified by the FATF include:
- Cash-Based Laundering / Smurfing (Structuring): Breaking down large volumes of illicit cash into small, less suspicious amounts to deposit into banks below reporting thresholds, or physically smuggling bulk cash across borders.
- Trade-Based Money Laundering (TBML): Misrepresenting the price, quantity, or quality of goods in import/export invoices to transfer illicit value across borders via legitimate commercial channels.
- Misuse of Shell/Front Companies and Complex Legal Structures: Creating multi-layered corporate arrangements, trusts, and anonymous shell companies to mask the identity of the true beneficial owners.
- Virtual Assets and Cryptocurrencies: Exploiting digital currencies, mixers, and decentralized exchanges to rapidly layer and move funds anonymously.
- Professional Money Laundering and Gatekeepers: Relying on complicit or corrupt third-party professionals—such as lawyers, accountants, and real estate agents—to set up financial schemes.
- Alternative Remittance Systems (Hawala): Utilizing informal, trust-based value transfer networks that operate completely outside conventional, regulated banking sectors.
- Co-mingling with Legitimate Cash-Intensive Businesses: Funnelling dirty money through high-cash-turnover businesses (like restaurants, casinos, or car washes) to blend it with lawful earnings.
- Purchase of High-Value Assets: Buying high-end real estate, luxury vehicles, precious metals, or art and antiquities to store and legitimize massive volumes of illicit wealth.
- Digital and Cyber-Enabled Fraud Networks: Using modern tech channels like online gaming, social media platforms, instant messaging apps, and online gambling to obscure financial flows.
How Should Environmental Investigators Follow the Money?
- Initiate a Parallel Financial Investigation
Financial investigation should commence alongside the environmental crime investigation rather than after completion of the prosecution of the predicate offence.
Investigators should examine:
- bank accounts and transaction histories;
- company ownership and beneficial ownership;
- invoices, contracts and purchase orders;
- customs and export documentation;
- tax records;
- payments to transporters and suppliers;
- cash withdrawals;
- cross-border transfers;
- related companies;
- property and other assets; and
- links with other criminal activities.
The objective is to move beyond the immediate offender and identify the financial controllers, beneficiaries and wider criminal networks.
- Use Financial Intelligence
Banks and other reporting entities can identify suspicious transactions and submit Suspicious Transaction Reports (STRs) to Financial Intelligence Units, subject to domestic law.
Environmental intelligence can significantly improve the value of financial intelligence. For example, unexplained transactions involving logging companies, substantial cash withdrawals near forest areas, payments to unlicensed suppliers, transactions involving geographically unrelated jurisdictions, or financial activity inconsistent with a company's declared business may warrant examination.
- Identify the Beneficial Owner
Environmental crime frequently operates through apparently legitimate companies. For example, the registered director of a timber company may not be the person controlling the illegal operation. Investigators must therefore look beyond nominal ownership and identify the natural person who ultimately owns or controls the enterprise. FATF's beneficial-ownership framework is particularly relevant where criminals use nominee shareholders, layered companies, offshore structures, trusts and professional intermediaries.
- Trace and Confiscate Criminal Assets
The objective should not merely be conviction for the environmental offence or money laundering. It should also be deprivation of the economic benefit of crime. Asset tracing should therefore begin at the earliest stage, followed by freezing, seizure and confiscation. FATF Recommendation 4 specifically addresses confiscation and provisional measures. For environmental enforcement, confiscation can be particularly important because it attacks the economic incentive underlying organised environmental crime.
FATF's Role: From Standards to Enforcement:
FATF does not itself investigate environmental crimes or prosecute environmental offenders. Its role is principally one of standard-setting, risk assessment, guidance, mutual evaluation and international coordination.
Its Recommendations provide countries with the architecture necessary to address environmental-crime proceeds, including:
- Recommendation 1: identification and assessment of money-laundering risks;
- Recommendation 3: criminalisation of money laundering;
- Recommendations 9–23: preventive measures applicable to financial institutions and relevant non-financial sectors;
- Recommendations 29–31: financial intelligence, investigation and law-enforcement responsibilities; and
- Recommendation 4: confiscation and provisional measures.
The FATF's environmental-crime work specifically encourages countries to incorporate environmental crime into national money-laundering risk assessments, strengthen financial-investigation capacity and improve cooperation between financial and environmental authorities.
Mutual Evaluations: The Compliance Mechanism
One of FATF's most significant tools for ensuring implementation is the mutual evaluation process. A country's AML regime is assessed not merely on whether legislation exists, but also on whether the system is effective in practice. For environmental crime, this provides an opportunity to examine whether a jurisdiction:
- has identified environmental crime as an ML risk;
- has criminalised relevant environmental offences and associated money laundering;
- has empowered environmental investigators, police, FIUs and prosecutors to conduct financial investigations;
- is generating and using financial intelligence in environmental cases;
- can identify beneficial ownership;
- investigates and prosecutes money laundering arising from environmental offences;
- traces, freezes and confiscates criminal proceeds;
- cooperates with foreign jurisdictions; and
- demonstrates actual cases and outcomes rather than merely legislative compliance.
Can FATF Put a Country on the Grey or Black List for Environmental Crime?
FATF maintains two principal categories:
- “Jurisdictions under Increased Monitoring”, commonly called the grey list, comprises jurisdictions working with FATF to address strategic deficiencies in their AML/CFT/CPF regimes.
- “High-Risk Jurisdictions subject to a Call for Action”, commonly called the black list, concerns jurisdictions with serious strategic deficiencies.
However, a country is not grey-listed or black-listed simply because it has high levels of illegal logging, wildlife trafficking or another environmental crime. Listing concerns deficiencies in the country's overall AML/CFT/CPF framework. For example, the Democratic Republic of the Congo (DRC) was put under “FATF increased monitoring” in 2026 because of broader AML/CFT deficiencies, including beneficial ownership, ML investigations and prosecutions and other institutional weaknesses; its presence on the list should not be described as a FATF listing for environmental crime. The more legally accurate proposition is that persistent failure to address money laundering risks arising from environmental crime could contribute to deficiencies identified during a mutual evaluation leading to listing of that country into Black/Grey List.
FATF's listing mechanism can function as an important external driver of AML effectiveness. Public identification as Grey/Black Listed creates political, reputational and financial incentives for jurisdictions to address strategic deficiencies. In this manner, FATF's mutual-evaluation and monitoring architecture can encourage jurisdictions to transform environmental-crime enforcement from a commodity-focused response into a comprehensive financial investigation of the criminal enterprise.
Conclusion
Environmental crime is profitable because criminal networks can convert natural resources into financial assets and integrate those proceeds into legitimate economic structures. FATF provides the framework to disrupt this process through risk assessment, financial intelligence, beneficial-ownership transparency, parallel financial investigations, asset tracing, confiscation and international cooperation.
For environmental law-enforcement agencies, the operational message is therefore simple:
Do not stop at the seized timber, wildlife, mineral or waste. Follow the financial trail. Identify the financier, facilitator, beneficial owner and ultimate beneficiary. Then take the profit out of the crime.
That is where environmental enforcement and financial enforcement converge—and where the FATF framework can make environmental crime a substantially higher-risk and lower-reward enterprise.
I am an Indian Revenue Service (Customs & Indirect Taxes) officer with vast experience of law enforcement especially in tackling transnational smuggling including willdife trafficking. Also, as an expert I have been conducting sessions on various aspects of wildlife crimes and its convergence with other serious crimes, legal and enforcement framework to counter it, wildlife cyber crime, OSINT for combating wildlife crime, combating money laundering associated with wildlife crime, CITES, role of Customs in tackling the menace of wildlife crime, Digital Forensics etc. for forest, police, customs and other enforcement agencies' officials.